Can You Get a Loan to Buy Bitcoin?


Ledn has over $10 billion in loan originations since 2018 and counting!
Yes—but using debt to buy Bitcoin magnifies both outcomes. If Bitcoin rises, the borrowed exposure can increase gains. If it falls, you still owe the debt and may also face liquidation, interest and fees.
There are three distinct routes: an unsecured loan, a loan secured by another asset, or a Bitcoin-backed product that uses your existing BTC to buy more. They should not be treated as interchangeable.
See how Ledn B2X works — review live availability, rate, fees and liquidation terms before considering the product. B2X is not available in every jurisdiction and has been wound down in Canada.
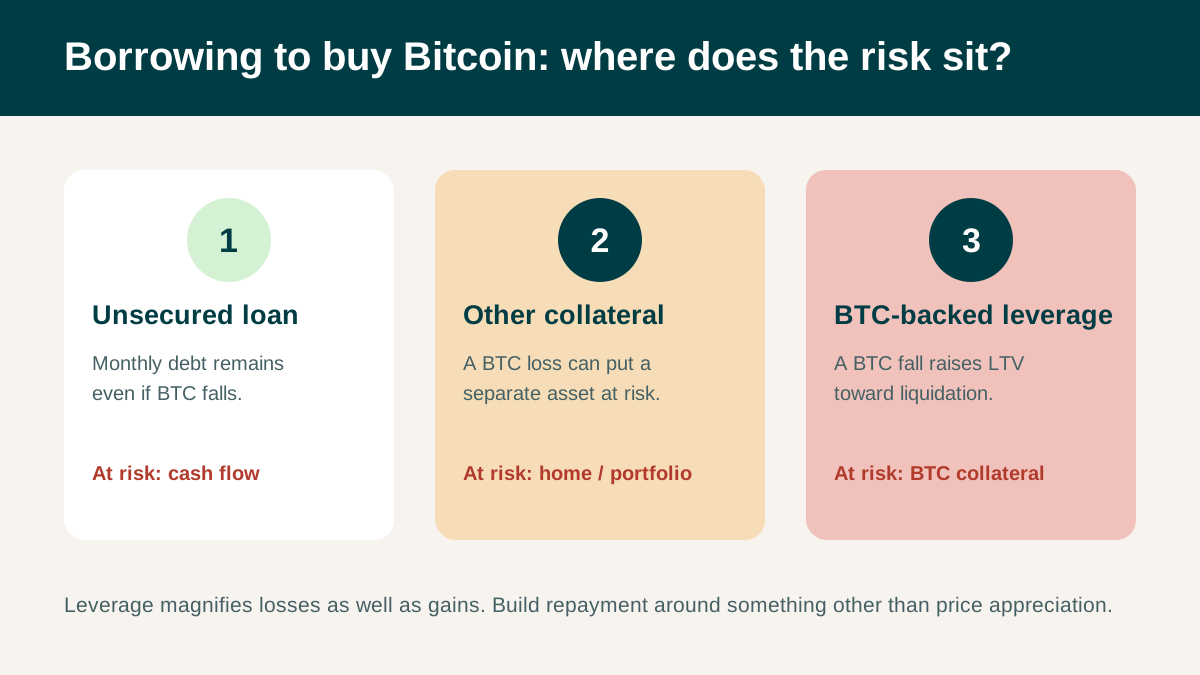
Three ways to finance a Bitcoin purchase
| Route | What secures the debt? | Main risk |
|---|---|---|
| Unsecured personal loan | Your promise and creditworthiness | Fixed repayments remain due even if BTC falls |
| Loan against another asset | Property, securities or other collateral | A Bitcoin loss can put a separate asset at risk |
| Bitcoin-backed leverage such as B2X | Existing BTC plus purchased BTC | Falling BTC raises LTV and can trigger liquidation |
1. An unsecured personal loan
A bank or lender may allow proceeds to be used for investment, but some agreements restrict crypto purchases. Approval, rate and limits usually depend on income and credit. Monthly payments are due regardless of Bitcoin's price.
This route avoids posting BTC as collateral, but it creates a cash-flow obligation. Read the permitted-use clause and calculate whether you could make every payment if Bitcoin fell sharply and remained lower for years.
2. Borrowing against another asset
Some people use a home-equity facility, securities-backed line or business loan to buy Bitcoin. That can provide a lower rate than a crypto-backed loan, but it links a volatile purchase to an asset or enterprise with a different purpose.
A Bitcoin decline does not reduce the debt. Depending on the agreement, a fall in the securing asset, a rate increase or a breach of covenant can also create problems. Professional legal, tax and financial advice is especially important here.
3. Using existing Bitcoin to buy more Bitcoin
Ledn's B2X product uses your existing BTC as collateral for a loan whose proceeds buy additional BTC. In a simplified example, a client contributes USD 10,000 of BTC, borrows USD 10,000 and uses the proceeds to buy more BTC, creating roughly USD 20,000 of BTC exposure before interest, fees and the execution spread.
That is leverage. It is not free Bitcoin and it does not guarantee doubled returns. The loan balance remains denominated in USD while the collateral value moves with BTC.
How B2X risk works
If BTC rises, the collateral value rises and LTV falls, which may allow eligible collateral redemption. If BTC falls, LTV rises. Ledn sends notifications at 70% and 75% LTV and automatically liquidates at or above 80%. A 0.50% trade spread applies where BTC is bought or sold.
At a 50% starting LTV, a roughly 37.5% fall in collateral value would move LTV to 80% if debt stayed constant. Interest and price adjustments can reduce the buffer. Bitcoin has experienced moves of that size before.
Before using B2X, decide:
- how much additional BTC you can add if LTV rises
- whether you would make a partial repayment instead
- the maximum loss you can accept
- how you will monitor the position during weekends and rapid markets
- whether the product is available where you live
B2X versus a standard Bitcoin-backed loan
A standard Bitcoin-backed loan gives you USD, local fiat where available, or an eligible stablecoin for an external use such as a property purchase, business capital, tax payment or major expense. B2X directs the borrowed value into more BTC.
The loan mechanics may be similar, but the purpose changes the risk. A standard loan can solve a liquidity need while retaining existing Bitcoin exposure. B2X deliberately increases that exposure.
Five questions before borrowing to buy Bitcoin
Can you repay without selling the Bitcoin?
Build the repayment plan around income or other liquid resources—not an assumption that BTC will be higher at maturity.
What happens if BTC falls 50%?
Model the numbers, including accrued interest. If the answer is “I would need to borrow more,” the position may be too large.
Is the rate fixed and what fees apply?
Check APR, origination or administration fees, spreads, repayment charges and renewal terms. Use the live offer rather than an article's example.
What happens at maturity?
For Ledn loans, eligible positions at or below 65% LTV may renew automatically under a new agreement where available. Otherwise the loan must be repaid or refinanced; if it is not resolved, collateral may be liquidated at maturity with no grace period.
How is collateral held?
For Ledn Custodied Loans, collateral may only be re-posted to an institutional USD funding partner or a Ledn-sponsored financing vehicle. Ledn says it remains in custody and is ring-fenced or bankruptcy-remote as applicable; it cannot be lent out to generate interest by Ledn or the partner.
When a loan to buy Bitcoin may not be suitable
It may be unsuitable if you lack an independent repayment source, would need a high LTV, cannot monitor the loan, have near-term cash needs, or could not tolerate losing collateral. Waiting, buying gradually with surplus cash, or not increasing exposure may be more appropriate.
Frequently asked questions
Can I borrow money to buy Bitcoin?
Some lenders permit it and products such as B2X are designed for it. Eligibility and permitted use depend on the provider and jurisdiction.
Does B2X double my profit?
No. It approximately doubles gross BTC exposure at origination in the simplified structure. Interest, fees, spread and price movement affect the result, while losses are also magnified.
Is borrowing to buy Bitcoin taxable?
Tax treatment varies. Loan proceeds, BTC purchases, collateral transfers, repayment with BTC and liquidation can be treated differently. Obtain advice for your jurisdiction.
Can I lose all my Bitcoin?
Liquidation can sell enough collateral to cover debt and costs, and severe market or platform events can create further losses. Read the agreement and risk disclosure.
Is there a credit check for B2X?
Ledn does not use a traditional credit check for its overcollateralised loans, although identity, location and eligibility checks apply.
Editorial sources
Related Ledn guides: Bitcoin loan rates, crypto lending platforms and Ledn security.
Borrowing to buy Bitcoin is high risk. This article is general information only and is not financial, investment, legal, accounting or tax advice. Bitcoin is volatile. Leverage can magnify losses, and a fall in collateral value can cause partial or full liquidation. Consider independent professional advice.
The experts opinions:

CTA Block 1
Ledn was created by people who believe in Bitcoin’s power to revolutionise finance and build wealth reliably.
CTA ButtonCTA Block 2
Ledn was created by people who believe in Bitcoin’s power to revolutionise finance and build wealth reliably.
CTA ButtonCTA Block 3
Ledn was created by people who believe in Bitcoin’s power to revolutionise finance and build wealth reliably.
CTA ButtonCTA Block 4
Ledn was created by people who believe in Bitcoin’s power to revolutionise finance and build wealth reliably.
CTA Button