Crypto Loans in Australia: How to Compare Platforms in 2026


Ledn has over $10 billion in loan originations since 2018 and counting!
Australians can access several types of crypto-backed borrowing, but a provider appearing in a global comparison does not mean its product is available to every Australian resident. Eligibility, payout currencies and legal terms can change.
This guide focuses on the practical questions: what collateral is accepted, what you receive, how your asset is held, and what happens if the market falls. Information was checked on 3 September 2026.
Check whether a Ledn Bitcoin-backed loan is available to you — view the indicative amount, rate and BTC requirement before applying.
Crypto loan options Australians may encounter
| Option | Model | Best understood as | Main point to verify |
|---|---|---|---|
| Ledn | Centralised, Bitcoin-focused | Fixed-rate loan against native BTC | Australian eligibility and available payout rail |
| Nexo | Centralised, multi-asset | Reusable crypto credit line | Jurisdiction, loyalty conditions and applicable rate |
| YouHodler | Centralised, multi-asset | Shorter-term crypto-backed loan | Current Australian availability, term and high-LTV risk |
| Aave | DeFi | Variable-rate onchain borrowing | Network, collateral token and health factor |
| Compound | DeFi | Borrowing a market's base asset | Market-specific collateral and liquidation parameters |
| CoinRabbit | Centralised service | Crypto-to-crypto borrowing | Contractual treatment of collateral and repayment terms |
This list is educational, not an endorsement. Some services may be unavailable or restricted in Australia when you read this.
Why Ledn may fit an Australian Bitcoin holder
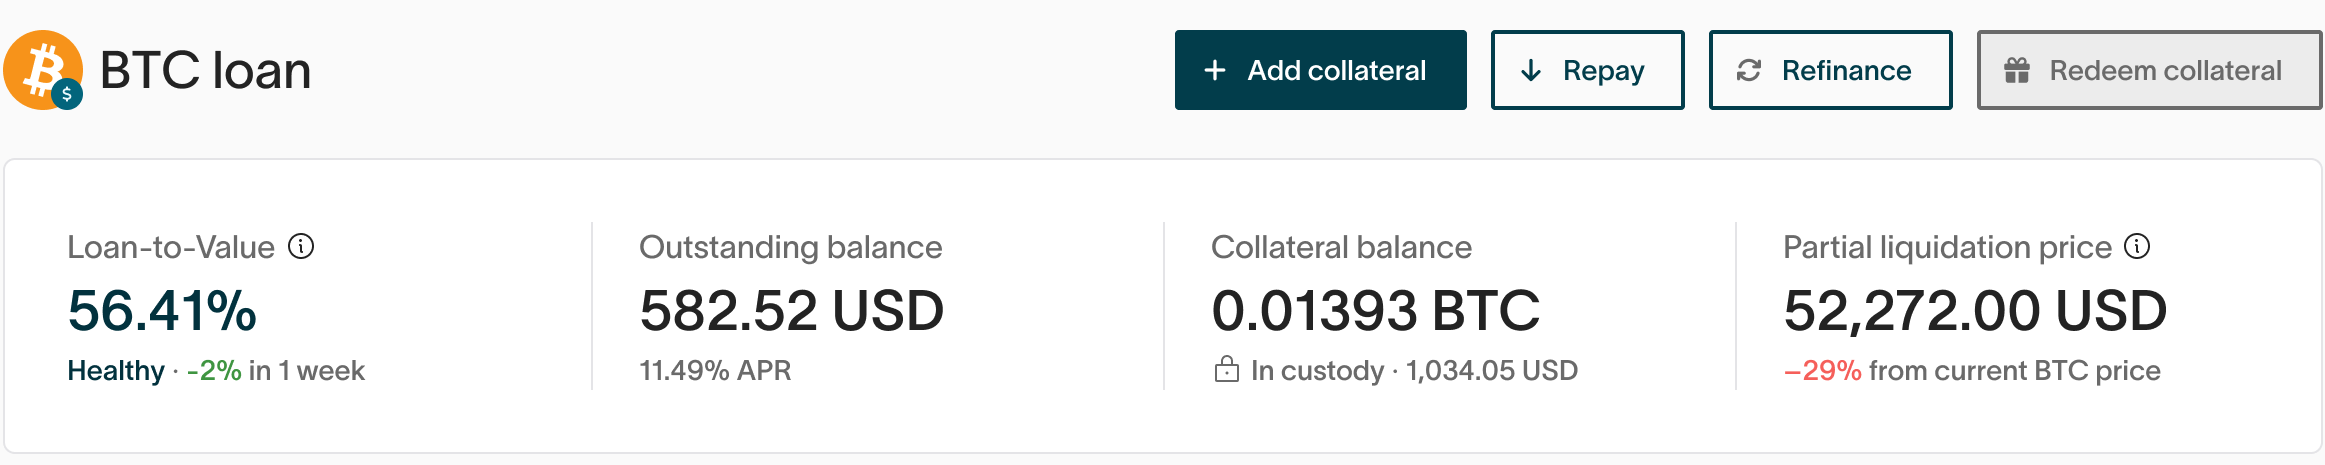
Ledn accepts native BTC as collateral and typically opens loans at 50% LTV. The minimum is USD 500, requiring at least USD 1,000 equivalent in Bitcoin. Published APR ranges from 11.49% to 9.25%, depending on the size of each individual loan, and the standard term is 12 months.
There is no traditional credit check, although identity, location and eligibility checks apply. Interest accrues daily, with no required monthly payments before closure and no early-repayment penalty.
The strongest fit is someone who holds Bitcoin and wants a defined, centralised loan rather than an onchain position. Ledn does not offer the permissionless access or broad altcoin collateral of a DeFi protocol.
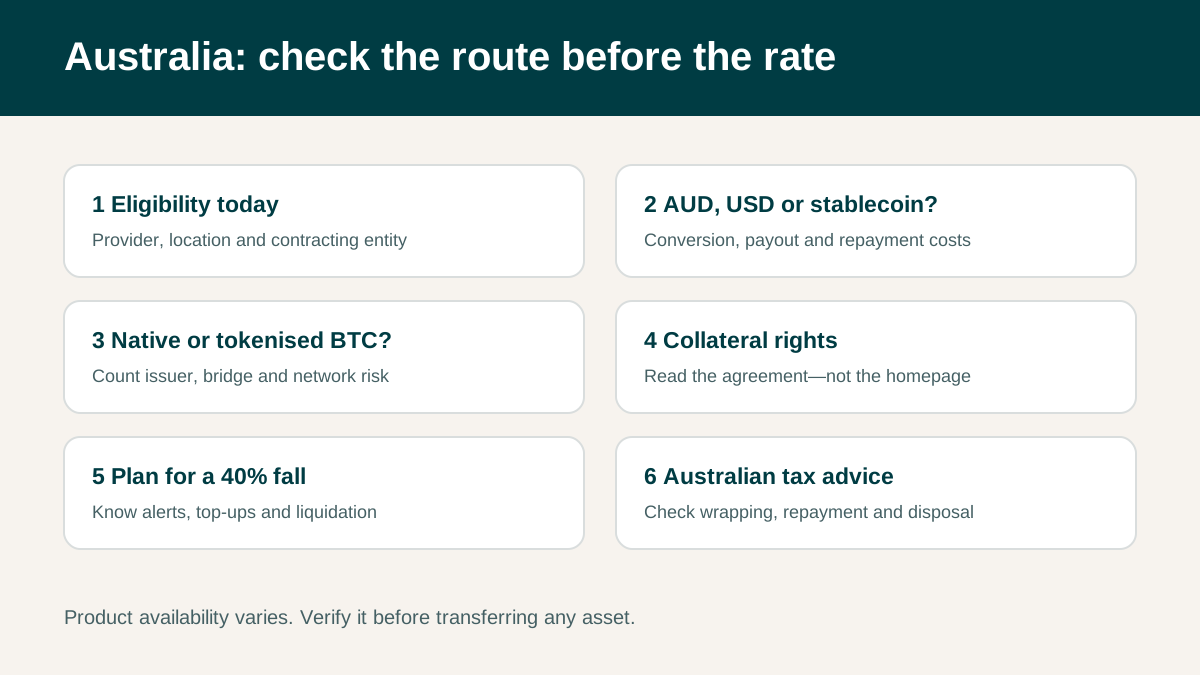
Six questions to ask before borrowing
1. Is the product currently offered in Australia?
Check the provider's eligibility page and the entity named in the agreement. Do not rely on a search result, review or account sign-up alone as proof that the loan is available.
2. Will you receive AUD, USD or a stablecoin?
The loan may be denominated in USD even if funds reach you through another rail. That can introduce conversion cost or currency exposure. Confirm disbursement, repayment and bank fees.
3. Are you posting native BTC or a tokenised version?
A centralised Bitcoin lender may accept BTC on the Bitcoin network. A DeFi protocol generally requires an onchain token compatible with its network. Tokenisation can add issuer, bridge, oracle, liquidity and smart-contract dependencies.
4. What can the provider do with collateral?
Read the agreement, not just a homepage. For Ledn Custodied Loans, collateral may only be re-posted to an institutional USD funding partner or Ledn-sponsored financing vehicle. Ledn says it remains in custody and is ring-fenced or bankruptcy-remote as applicable; it cannot be lent out to generate interest by Ledn or that partner.
5. How will you handle a 30%–40% Bitcoin fall?
At Ledn, notifications are sent at 70% and 75% LTV and liquidation occurs automatically at or above 80%. Eligible users can enable Auto Top-Up at 70%, targeting 68%, or make a partial repayment. Other providers and DeFi markets use their own triggers and penalties.
6. What is the Australian tax treatment?
Borrowing and selling are different transactions, but collateral conversion, repayment with crypto or liquidation may have tax consequences. Obtain Australian tax advice for your situation; this article does not determine the treatment.
Centralised crypto lenders vs DeFi in Australia
Centralised lenders may offer support, fiat rails and a contract with an operating company. In return, the borrower accepts custody and counterparty risk. DeFi protocols expose rules and positions onchain and may not require a traditional application, but add wallet, smart-contract, oracle, network and liquidation-bot risk.
Neither model makes risk disappear. It changes where trust sits and how failures are resolved.
How Ledn manages a Bitcoin-backed loan
- Apply and complete the required identity and eligibility checks.
- Review the rate, fee, term and payout options shown for your account.
- Transfer the required BTC to the loan address.
- Receive funds through an available fiat or stablecoin method.
- Monitor LTV, add collateral or repay if the Bitcoin price falls.
- Repay the principal and accrued interest; remaining collateral is released.
Ledn has originated more than USD 11 billion of loans since 2018. Its Open Book Report and Proof of Reserves provide additional information about operations and assets, but no disclosure removes all lending risk.
Frequently asked questions
Can Australians get a crypto-backed loan?
Some eligible Australian residents may be able to use crypto-backed lending services, subject to the provider's current location rules and checks. Confirm availability before transferring assets.
Can I borrow Australian dollars against Bitcoin?
Payout methods vary. A loan may be denominated in USD and paid through an available fiat or stablecoin rail. Check currency conversion, bank fees and repayment instructions.
What is a safe LTV for a Bitcoin loan?
There is no risk-free LTV. A lower starting LTV generally creates more room before liquidation but requires more collateral for the same loan. Stress-test the position against a large Bitcoin decline.
Do crypto lenders check credit scores?
Some overcollateralised crypto lenders do not use a traditional credit check. Identity, sanctions, location and product checks may still apply.
What happens if my collateral is liquidated?
The provider or protocol sells collateral to reduce or close the debt. You may lose part of your Bitcoin and the sale may have tax consequences.
Editorial sources
Related Ledn guides: Bitcoin loan rates, crypto lending platforms and Ledn security.
- Ledn Bitcoin-backed loans
- Ledn Loans Help Center
- Nexo Credit Line
- YouHodler loan guide
- Aave borrowing guide
- Compound III collateral and borrowing
- CoinRabbit terms
This article is general information only and is not financial, investment, legal, accounting or tax advice. It does not confirm that any product is available in Australia. Digital assets are volatile; a fall in collateral value can lead to liquidation and financial loss. Verify all terms and seek independent professional advice.
The experts opinions:

CTA Block 1
Ledn was created by people who believe in Bitcoin’s power to revolutionise finance and build wealth reliably.
CTA ButtonCTA Block 2
Ledn was created by people who believe in Bitcoin’s power to revolutionise finance and build wealth reliably.
CTA ButtonCTA Block 3
Ledn was created by people who believe in Bitcoin’s power to revolutionise finance and build wealth reliably.
CTA ButtonCTA Block 4
Ledn was created by people who believe in Bitcoin’s power to revolutionise finance and build wealth reliably.
CTA Button